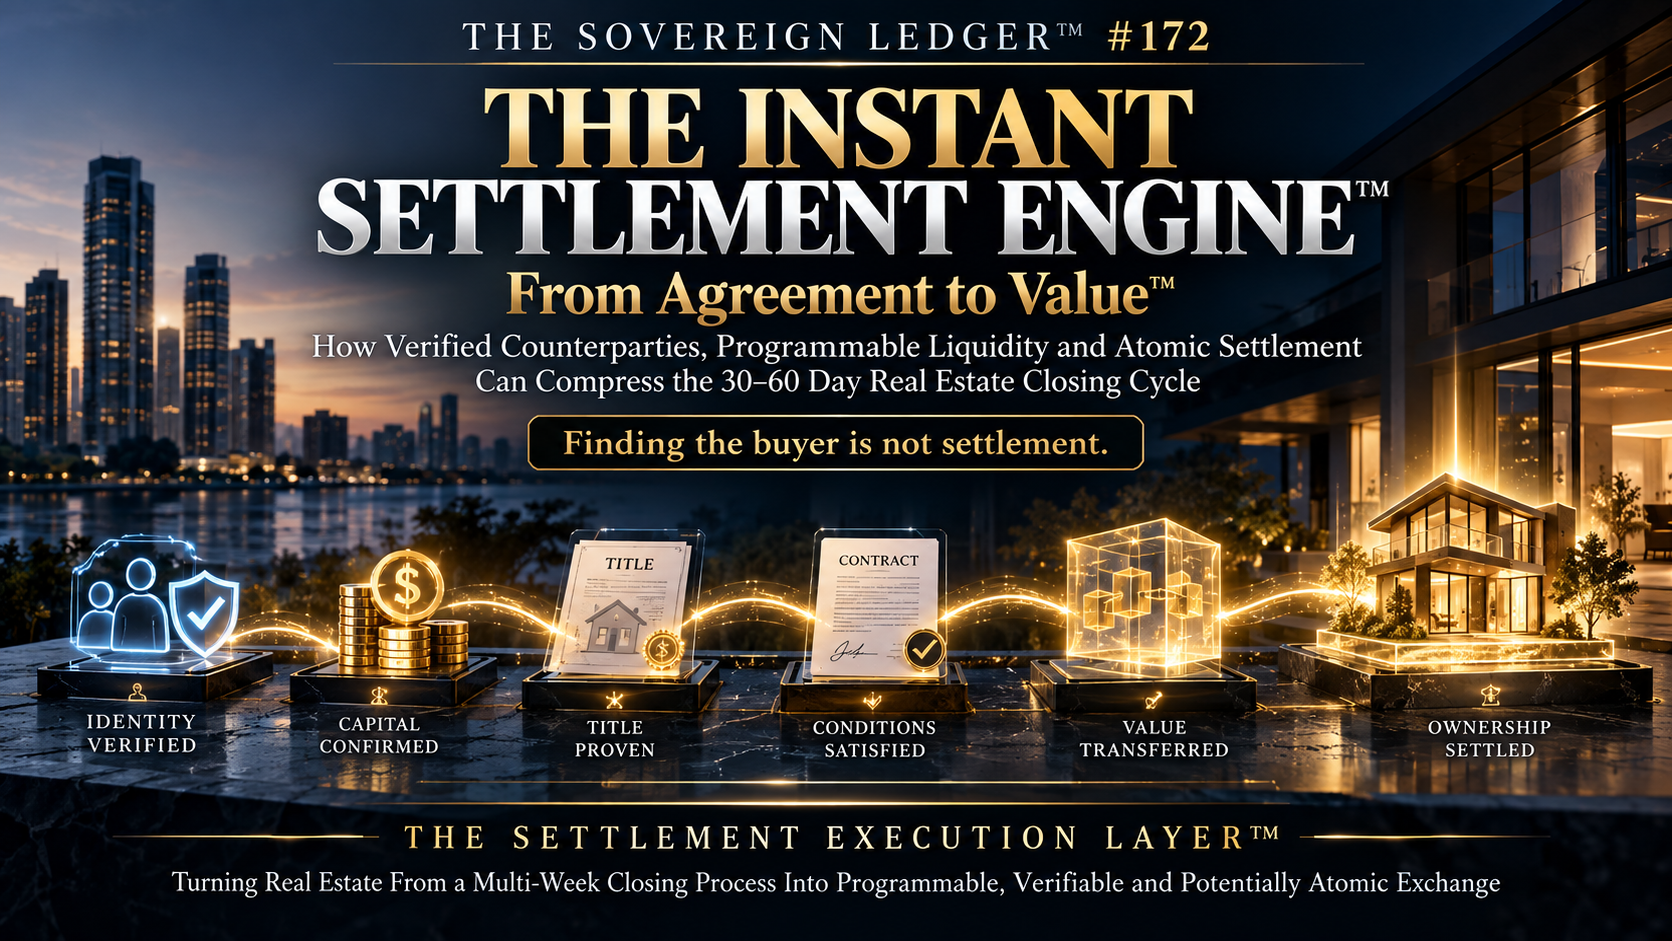
THE SOVEREIGN LEDGER™ · ENTRY #172 · SEPTEMBER 2026
THE OWNERSHIP THESIS™ WEEKLY RESEARCH REPORT
THE INSTANT SETTLEMENT ENGINE™
From Agreement to Value™: How Verified Counterparties, Programmable Liquidity and Atomic Settlement Can Compress the 30–60 Day Real Estate Closing Cycle
Friday, September 25, 2026 · Eastern Time
Palm Beach · Miami · Sarasota · New York
Finding the buyer is not settlement.
Signing the contract is not settlement.
Moving the money is not settlement.
Settlement occurs when identity, authority, capital, law and ownership converge.™
THE SOVEREIGN ARCHITECTURE · CORPUS RECORD AT PUBLICATION · SEPTEMBER 25, 2026 (ET)
172 Bitcoin-Anchored Entries · 2.62M+ Verified Words · 260+ Audiobook-Equivalent Hours · 800+ Strategic Blueprints
1.55B+ Reported Global Network / Reach Footprint · SHA-256 · OpenTimestamps · Bitcoin-Anchored Provenance
Methodology: 10,000 verified words ≈ one audiobook-equivalent hour (≈166.7 WPM). Methodology & Proof → Provenance™
OBSERVE · THINK · PROVE · BUILD
INTRODUCTION
Entry #171 addressed global reach: how a local asset becomes visible and commercially relevant to qualified capital anywhere on Earth. But global distribution immediately exposes the next bottleneck. The moment the right buyer arrives, the distribution problem ends and the settlement problem begins.
Across much of the real estate industry — brokerage, lending, title, escrow and private-client wealth alike — closing still runs as a sequential chain of disconnected databases, paper-era reconciliations, manual approvals, banking windows and siloed legal dependencies. That chain can consume weeks between financing approval and finality.
The market does not require zero diligence. It requires zero avoidable latency once diligence is complete. The objective is simple: protect necessary friction while eliminating avoidable friction. Entries #169 through #172 now form The Sovereign Transaction Quad™ — the complete execution layer:
Entry #169 — The Authoritative Ownership Record™: establishes Truth.
Entry #170 — The Legal Control Layer™: establishes Law.
Entry #171 — The Global Distribution Control Layer™: establishes Demand.
Entry #172 — The Instant Settlement Engine™: executes Settlement.
ICE Mortgage Technology reported that the average U.S. purchase mortgage closed in 36.8 days in March 2026 — the fastest average since ICE began tracking the metric in 2019. The typical purchase loan took 11 days to move from application to rate lock, then another 26 days from rate lock to closing. That is real progress. It is also a friction budget measured in weeks, in an era when information moves in milliseconds.
Closing is not a single signatures-and-wire event. It is a multi-variable state-transition orchestration problem. Legacy platforms ask, “Where is the document?” Programmable infrastructure asks, “Has the condition been satisfied?”
By deploying the Verified Counterparty Rail™ — verifying identity, beneficial ownership, legal authority, regulatory eligibility and economic capacity — the architecture removes low-value administrative friction before execution. T-0 does not mean zero diligence. T-0 means zero avoidable latency from the moment every condition on the Conditions-to-Close Graph™ becomes true.
EXECUTIVE THESIS
Entry #171 solved the problem of distance.
The customer is already global.
The property is still local.
The infrastructure between them should no longer be.™
The Global Distribution Control Layer™ asked how a local asset could become visible, understandable and commercially relevant to qualified capital anywhere in the world.
But distribution creates a new problem.
Suppose the buyer has been found.
Suppose the asset is understood.
Suppose the parties agree on economics.
Suppose the capital exists.
Suppose both sides want to close.
What happens next?
In much of real estate, the answer remains a sequence of disconnected systems, people, documents, reconciliations, approvals, banking windows, title processes and legal conditions that can consume weeks.
That is the gap Entry #172 addresses.
THE DISTRIBUTION PROBLEM ENDS WHEN THE RIGHT BUYER ARRIVES.
THE SETTLEMENT PROBLEM BEGINS.
And this is where the distinction between a better marketing platform and genuine ownership infrastructure becomes decisive.
A portal can generate a lead.
A broker can negotiate an agreement.
A lender can approve credit.
A title professional can examine ownership.
An attorney can establish legal requirements.
A bank can move money.
A recorder can update the public record.
A blockchain can preserve state and chronology.
A cryptographic system can provide evidence.
But unless those functions can be coordinated around a common transaction state, each participant remains dependent on the next handoff.
The problem is not that each function exists. The problem is that the functions frequently operate sequentially, across disconnected systems, with repeated verification, manual reconciliation and uncertain visibility into whether the next condition has actually been satisfied.
That is the settlement problem. And it leads directly to the thesis of #172:
REAL ESTATE DOES NOT NEED ZERO DILIGENCE.
IT NEEDS ZERO AVOIDABLE LATENCY AFTER DILIGENCE IS COMPLETE.™
That distinction is essential.
The goal is not to make title examination disappear.
It is not to eliminate attorneys where law requires or benefits from legal judgment.
It is not to eliminate lenders, banks, escrow professionals, title professionals or regulators simply because technology exists.
It is not to replace property law with code.
And it is certainly not to move millions of dollars merely because an AI agent says “approved.”
The objective is more disciplined:
PROTECT NECESSARY FRICTION.
ELIMINATE AVOIDABLE FRICTION.™
That is the foundation of The Instant Settlement Engine™.
WHY THIS WINDOW IS OPEN NOW
What changed in 2026 is that the world’s largest financial institutions stopped discussing settlement innovation and started operating it.
EXHIBIT A — WHO IS ALREADY BUILDING THE RAILS (MEASURED FACTS)
J.P. Morgan: its Kinexys blockchain payments platform had processed more than $3 trillion in cumulative volume since launch and was averaging more than $5 billion a day as of spring 2026, with a stated ambition to exceed $10 billion a day.
HSBC: launched its Tokenized Deposit Service in the United States on April 13, 2026 and in the UAE on June 22, 2026, offering eligible corporate clients 24/7 domestic and cross-border transfers on blockchain rails, alongside Hong Kong, Singapore, Luxembourg and the UK.
The Clearing House: its RTP network processed more than $1.3 trillion in 2025 — up 428% from $246 billion in 2024 — and $481 billion in Q1 2026 alone, under a per-transaction limit raised to $10 million.
The Federal Reserve: FedNow raised its transaction limit twice in 2025, reaching $10 million in November.
The BIS: Project Agorá settled real value atomically across six currencies in July 2026, with J.P. Morgan, Citi, UBS and central banks among the 28 participants.
ICE: the MERS eRegistry surpassed 3 million eNotes in March 2026; lenders at the forefront now register 30% to 80% of their originations digitally.
EXHIBIT B — WHERE THE FORECASTERS SAY IT GOES (FORECASTS, NOT FACTS)
McKinsey & Company: tokenized financial assets tracking toward roughly $2 trillion by 2030 (excluding cryptocurrencies and stablecoins), with a bullish case near $4 trillion.
BCG with Ripple: tokenized assets could reach $18.9 trillion by 2033 — a different scope that includes stablecoins and tokenized deposits.
Deloitte Center for Financial Services: roughly $4 trillion of real estate could be tokenized by 2035.
IDC: worldwide AI spending reaching $1.3 trillion in 2029, driven by agentic AI, growing 31.9% a year from 2025.
These forecasts use different scopes, definitions and dates. They are shown side by side for direction, not added together, and none is a measurement of today’s market.
None of those institutions is settling a Palm Beach deed atomically today. They are building always-on, programmable money rails that real estate will eventually be asked to plug into.
That creates an asymmetry. When the payment layer can settle in seconds, every day a property transaction spends waiting becomes more visible — to buyers, to sellers, to lenders, to family offices and to the next generation of owners who have never experienced money that sleeps on weekends.
THE MONEY IS LEARNING TO MOVE AT THE SPEED OF SOFTWARE.
THE QUESTION IS WHETHER OWNERSHIP WILL KEEP UP.
The firms that design their settlement architecture during this window will set the standards others inherit. The firms that wait will integrate with somebody else’s standard — on somebody else’s terms. I laid out that dynamic in Entry #166, The Sovereign Control Plane™, and in Entry #158, Own the Rails, Not the Model. #172 applies it to the final mile: settlement.
I. THE SOVEREIGN TRANSACTION QUAD™
Entries #169 through #172 now form a coherent transaction architecture. They should be understood together.
#169 — THE AUTHORITATIVE OWNERSHIP RECORD™ · THE TRUTH
Which record actually represents the authoritative ownership state?
Entry #169 established a distinction that should govern everything that follows: cryptographic integrity is not the same thing as legal ownership. A token, blockchain entry, smart contract, corporate record and county deed may each represent different rights or claims. The architecture must determine which source is authoritative for the right being transferred.
#170 — THE LEGAL CONTROL LAYER™ · THE LAW
Which legal rights, jurisdictions, agreements and ownership structures ultimately govern?
A technologically perfect record is useless if the parties misunderstand what the law recognizes.
#171 — THE GLOBAL DISTRIBUTION CONTROL LAYER™ · THE DEMAND
How does the legitimate asset become globally discoverable to relevant buyers, investors, family offices, developers and capital?
The customer is global.
The asset is local.
Distribution connects them.
#172 — THE INSTANT SETTLEMENT ENGINE™ · THE EXECUTION
Once truth, law, demand and capital converge:
How does value actually move?
The sequence becomes:
TRUTH → LAW → DEMAND → EXECUTION™
That is the Sovereign Transaction Quad™.
#169 established what must be trusted.
#170 established what must legally control.
#171 established how qualified demand can find the asset.
#172 asks the unavoidable final question:
ONCE BUYER, SELLER, ASSET, LAW AND CAPITAL CONVERGE, WHY SHOULD AVOIDABLE SETTLEMENT LATENCY REMAIN?
II. THE FRICTION PARADOX™
Real estate has a paradox.
The asset may be extraordinarily valuable.
The buyer may have the money.
The seller may have title.
The agreement may already exist.
Yet the value cannot immediately move.
ICE’s 36.8-day purchase-closing average for March 2026 is a record. That is progress. It also exposes the opportunity — especially when you set it beside the rest of the infrastructure economy.
The Internet transmits information globally in milliseconds.
AI can analyze thousands of pages in seconds.
Starlink reported a median peak-hour latency of 25.7 milliseconds for U.S. customers in its July 2025 network update — a satellite constellation answering in about a fortieth of a second.
The Federal Reserve’s FedNow Service settles participating instant payments within seconds, 24 hours a day, 365 days a year.
The Clearing House’s RTP network accounts for 98% of U.S. bank-to-bank instant payments and now supports individual payments up to $10 million.
The BIS has demonstrated cross-border atomic settlement using tokenized commercial-bank deposits and tokenized central-bank reserves.
And yet the purchase of a house can still consume more than a month between financing application and closing.
Why?
Because moving money is only one component of settlement. Property settlement combines identity, authority, property rights, legal documentation, title, liens, financing, disclosures, taxes, insurance, diligence, signatures, escrow, payment, recording, regulatory requirements, fraud prevention and finality.
That is why simply putting dollars onto a blockchain does not solve real estate.
THE BOTTLENECK IS NOT MONEY ALONE.
THE BOTTLENECK IS COORDINATION OF CONDITIONS.
III. CLOSING IS NOT AN EVENT. IT IS AN ORCHESTRATION PROBLEM.
The term “closing” makes the process sound deceptively simple.
One day.
One table.
One signature ceremony.
One wire.
One set of keys.
Operationally, closing is closer to a state-transition system. Every required state must become acceptable before the final ownership state can change.
Consider the questions hidden inside a single transaction:
Is the buyer who they claim to be?
Is the seller who they claim to be?
Does the seller actually control the property?
If an LLC owns the property, who controls the LLC?
If a trust owns it, who can bind the trust?
Are signatures authorized?
Are there liens?
Are taxes current?
Does another party possess a superior claim?
Is financing unconditional?
Has appraisal been completed?
Has diligence been satisfied?
Are required disclosures complete?
Have contractual contingencies been released?
Are payment instructions authentic?
Can the receiving institution accept the funds?
Is the deed legally sufficient?
Can it be recorded?
Does the jurisdiction support electronic recording?
What constitutes finality?
The transaction does not close because someone clicks SEND. It closes because the entire set of legally required conditions reaches an executable state.
That gives us one of the central ideas of Entry #172:
LEGACY CLOSING ASKS: “WHERE IS THE DOCUMENT?”
PROGRAMMABLE SETTLEMENT ASKS: “HAS THE CONDITION BEEN SATISFIED?”™
That is the movement from document-centric closing toward a state-aware transaction architecture.
IV. THE REAL ESTATE FRICTION BUDGET™
Not all friction is bad. This distinction is critical.
Some friction exists because the underlying system is antiquated. Some exists because somebody must prevent fraud, establish rights or protect the customer. The second category should not be casually deleted.
The Consumer Financial Protection Bureau requires most covered mortgage borrowers to receive their Closing Disclosure at least three business days before closing, so they have time to review final loan terms and costs. That is intentional friction. It serves a consumer-protection purpose.
Likewise, title examination may uncover defects — an undisclosed heir, an unreleased lien, a break in the chain of title — that genuinely need curative work before clean, insurable title can be delivered.
So the correct first-principles question is not, “How do we delete every step?” It is:
WHAT RISK DOES THIS STEP PROTECT AGAINST?
If the answer is meaningful, preserve the protection and improve the process. If the answer is duplication, inertia or an obsolete technological dependency, redesign it.
I define five categories inside the Real Estate Friction Budget™:
TIME FRICTION — elapsed time created by waiting, sequencing, office hours, document transfer and manual approval.
INFORMATION FRICTION — repeated data entry, conflicting records, duplicate verification, missing documents and reconciliation.
CAPITAL FRICTION — money reserved, escrowed, unavailable or unable to be redeployed while conditions remain unresolved.
INTERMEDIARY FRICTION — costs and delays created by coordination among independent parties and systems.
RISK FRICTION — time and controls deliberately imposed to reduce title, identity, credit, compliance, fraud and legal risk.
The architecture should attack the first four aggressively. It should attack the fifth intelligently.
As Entry #167, The Cost of Control™, showed in comparing Manhattan and Florida, friction is a line item — in time, carrying cost and capital that cannot yet be redeployed.
DO NOT AUTOMATE UNCERTAINTY.
RESOLVE IT — THEN AUTOMATE EXECUTION.™
V. THE VERIFIED COUNTERPARTY RAIL™
This is where my earlier concept of The Verified Counterparty Layer™ belongs. Not as a separate, competing Entry #172 — inside the settlement engine. Because before any transaction can become atomic, the system needs to know who is actually standing on both sides.
A LEAD IS NOT A BUYER.
A WALLET IS NOT AN IDENTITY.
A BANK BALANCE IS NOT TRANSACTION AUTHORITY.
GLOBAL REACH IS NOT QUALIFIED CAPITAL.™
The verified counterparty architecture must answer at least five distinct questions.
1. IDENTITY — Who is the natural person?
2. BENEFICIAL OWNERSHIP — If a company, trust, SPV or other entity is involved, who ultimately controls or benefits from it?
3. AUTHORITY — Does this person possess the legal authority to bind the buyer, seller, trust, entity or fund?
4. ELIGIBILITY — Can this counterparty legally participate in this transaction under the relevant sanctions, AML, securities, foreign-ownership, financing and property rules?
5. CAPACITY — Can the buyer actually perform economically?
These are different questions.
A passport can establish identity without establishing authority.
A corporate registration can establish entity existence without proving the signer has authority.
Proof of funds can establish available money without establishing its permissible source.
A crypto wallet can demonstrate control over a private key without proving the legal identity of the controller.
That is why counterparty verification cannot be an afterthought.
VI. WHY IDENTITY HAS BECOME MORE IMPORTANT, NOT LESS
Digital settlement does not eliminate fraud. If identity controls are weak, it can make fraudulent execution faster. That is why the 2026 fraud evidence matters.
On September 14, 2026, the American Land Title Association released its 2026 seller-impersonation fraud study. Based on 245 title professionals, it found that 59% of firms encountered at least one seller-impersonation attempt in the prior calendar year — more than double the 28% in ALTA’s 2024 survey. The share reporting an attempt in the month before the survey rose from 19% to 45%, and 23% reported three or more attempts that month, up from 4%.
Among firms that reported an attempt, one in four paid a claim; among those disclosing the amount, half said the average payout exceeded $100,000. Spoofed contact information was cited as at least a somewhat common tactic by 87% of firms, and 58% had encountered deepfaked images or voices — two categories that did not even appear in the 2024 survey.
Vacant land remained the most common target, but vacation homes, rental properties, agricultural land and primary residences also appeared — alongside properties tied to absentee and deceased owners.
ALTA’s 2026 sample was smaller and weighted toward higher-volume, multistate firms than its 2024 study; ALTA reported that weighting the results did not change its findings.
This leads to a critical principle:
FASTER SETTLEMENT WITHOUT STRONGER IDENTITY CAN CREATE FASTER FRAUD.
That is not progress. The Instant Settlement Engine™ therefore begins with verification, not velocity.
VII. THE REGULATORY LANDSCAPE IS MOVING TOO
The U.S. regulatory architecture around real estate counterparty reporting remains in flux.
On March 19, 2026, the U.S. District Court for the Eastern District of Texas vacated FinCEN’s Residential Real Estate Rule in Flowers Title Companies, LLC v. Bessent, holding that FinCEN exceeded its authority under the Bank Secrecy Act. FinCEN appealed to the U.S. Court of Appeals for the Fifth Circuit on May 11, 2026. While the order remains in force, covered parties are not required to file Real Estate Reports under that rule.
That should not be read to mean identity and beneficial ownership no longer matter. It means the precise regulatory mechanism is contested — and could return.
The architectural requirement remains. A serious ownership platform must understand who the counterparties are, what entity structures sit between them and the asset, what authority exists and what compliance requirements apply to that particular transaction.
Compliance cannot be hard-coded to yesterday’s rulebook. It needs jurisdictional awareness. And it must be updateable.
PROGRAMMABILITY WITHOUT LEGAL ADAPTABILITY BECOMES TECHNICAL DEBT.
VIII. THE CONDITIONS-TO-CLOSE GRAPH™
This may be the single most important new architecture inside #172.
A property transaction should not merely be represented as a folder of documents. It should increasingly be understood as a graph of required conditions and dependencies. I call it:
THE CONDITIONS-TO-CLOSE GRAPH™
EXHIBIT C — THE CONDITIONS-TO-CLOSE GRAPH™ (CONCEPTUAL)
| Condition | Typical owner | Depends on |
|---|---|---|
| Buyer identity verified? | Buyer-side KYC provider / lender | — |
| Seller identity verified? | Title / closing agent | — |
| Seller authority verified? | Attorney / title | Seller identity; entity or trust documents |
| Authoritative ownership record confirmed? | Title | Seller authority |
| Title exceptions identified and curative items resolved? | Title / attorney | Authoritative record |
| Proof of funds verified; financing approved? | Lender / private bank | Buyer identity |
| Source-of-funds and compliance requirements satisfied? | Compliance / bank | Buyer identity; jurisdiction |
| Disclosures delivered and waiting periods complete? | Lender | Financing approval |
| Inspection, diligence and contingencies released? | Buyer / counsel | Contract |
| Tax, lien and insurance requirements satisfied? | Title / insurer | Title exceptions |
| Execution documents complete? | Attorney / notary | All legal conditions |
| Payment rail ready; recording channel ready? | Bank / recorder | Verified payment instructions |
| ALL REQUIRED CONDITIONS TRUE? | → SETTLEMENT ENABLED | |
Illustrative only. Actual conditions, owners and dependencies vary by jurisdiction, financing structure and transaction type.
That is a fundamentally different way to think about closing.
Instead of asking one closing coordinator to mentally track twenty variables scattered across emails, PDFs, portals, phone calls and spreadsheets, the system models the transaction as an observable set of states.
Not every state has to sit on-chain.
Not every underlying document should be public.
Not every decision can be automated.
But the system can know that a condition exists, which party is responsible for it, whether it has been satisfied, what evidence supports that conclusion and which condition depends on it next.
CLOSING BECOMES A CONTROL PLANE.
IX. T-0 BEGINS AFTER T-MINUS EVERYTHING™
This is the conceptual correction that makes the entire REALATAR™ settlement thesis stronger.
T-0 does not mean, “We found a buyer Monday morning and transferred the house by lunch.” That would confuse diligence time with settlement time. Instead:
T-0 DOES NOT MEAN ZERO DILIGENCE.
T-0 MEANS ZERO AVOIDABLE LATENCY ONCE ALL REQUIRED CONDITIONS ARE SATISFIED.™
Think of the transaction as two phases.
PHASE ONE — T-MINUS
Identity · Diligence · Underwriting · Inspection · Appraisal · Title examination · Legal review · Financing · Compliance · Disclosures · Negotiation · Conditions precedent
This phase can take time because it involves real investigation, human decisions and legally required waiting periods.
PHASE TWO — T-0
Once every prerequisite condition is satisfied: lock the appropriate states, authorize value movement, execute the required instruments, coordinate payment, coordinate ownership transfer, submit recording, update recognized records, release funds where permitted, preserve transaction evidence and publish the appropriate provenance state.
That final interval is where atomic settlement principles become transformative.
Entry #161, The Programmable Ownership Execution Standard™, already established this distinction: REALATAR™ should coordinate the point at which required conditions have been satisfied, and true T-0 real estate settlement remains an objective rather than the current universal condition, because banking, title, legal conveyance, recording, identity and regulatory systems must all interoperate. #161 mapped the path — identity, asset, capital, title, settlement, provenance, continuous ownership. #172 turns that earlier principle into a complete settlement architecture.
X. THE DIGITAL MORTGAGE IS ALREADY ARRIVING
This is not science fiction. The U.S. mortgage system has already begun converting important components from paper into digitally authoritative instruments.
On March 11, 2026, ICE announced that the MERS eRegistry had surpassed 3 million eNotes. MERS System data showed that lenders at the forefront of adoption are now registering between 30% and 80% of their originations digitally. The eRegistry, together with more than 500 participants and their eVaults, provides an industry-wide system of record for who controls each eNote and where the authoritative copy lives.
Fannie Mae defines an eClosing as a mortgage closing in which some or all documents are accessed and executed electronically, and an eMortgage as one involving an electronically signed promissory note registered through the MERS eRegistry.
The legal and operating architecture already involves electronic signatures, eNotes, eVaults, authoritative electronic copies, registry control, digital closing platforms and electronic notarization. Remote online notarization is now authorized by statute or executive order in nearly every U.S. state, although requirements remain jurisdiction-specific. And the Property Records Industry Association maintains electronic-recording standards and a current list of jurisdictions that support eRecording.
The conclusion is not that American title infrastructure has become fully digital. It has not. The conclusion is more important:
THE CLOSING STACK IS ALREADY BECOMING DIGITAL.
THE NEXT QUESTION IS WHETHER IT BECOMES INTEGRATED.™
XI. DIGITIZATION IS NOT ATOMICITY
This is the same distinction I have made throughout my Real Estate Innovation work. Digitizing paper is not the same thing as redesigning the architecture.
An electronic PDF can still sit in someone’s inbox for three days.
An e-signature can still be followed by six manual reconciliations.
A digital title report can still require another employee to re-key the data somewhere else.
A wire can arrive instantly while somebody waits hours to verify it.
An electronically executed deed can still sit in a recording queue.
is digitization — important, but incrementalDISCONNECTED DIGITAL STEPS → COORDINATED TRANSACTION STATE
is architectural transformation
The broader economy is learning the same lesson with AI. PwC’s 29th Global CEO Survey, published in January 2026 and based on 4,454 CEOs in 95 countries and territories, found that 56% had seen neither higher revenue nor lower costs from AI in the prior 12 months; only 12% reported both. PwC’s own conclusion was that isolated, tactical AI projects often fail to deliver measurable value, and that tangible returns come from enterprise-scale deployment built on strong foundations.
Accenture’s payments research points in the same direction: it found that only 20% of banks possess the foundations to capitalize quickly on new payment opportunities.
ISOLATED DIGITAL FEATURES DO NOT COMPOUND.
INTEGRATED ARCHITECTURE DOES.
XII. PROGRAMMABLE LIQUIDITY™ — MONEY IS BECOMING SOFTWARE-AWARE
Real estate cannot settle faster than the money available to settle it. But the monetary infrastructure is changing rapidly.
FedNow supports near-real-time interbank settlement around the clock. The RTP network also runs continuously, with final interbank settlement and immediate availability of received funds through participating institutions. Both now accept individual payments of up to $10 million.
These systems demonstrate an important fact: 24/7 bank-account money movement is no longer theoretical. The next layer is programmability.
The United States enacted the GENIUS Act on July 18, 2025, creating a federal statutory framework for payment stablecoins. But precision matters here too. On August 18, 2026, Treasury issued a further notice of proposed rulemaking under the Act. Because final regulations are not expected in time to trigger an earlier date, the Act is expected to take effect on January 18, 2027 — its statutory outside date. FinCEN and OFAC have also proposed AML and sanctions requirements for permitted payment stablecoin issuers, and the federal banking agencies have issued their own proposals.
Therefore #172 should not say, “GENIUS Act–compliant stablecoin settlement is already universally live.” That would outrun the evidence. The more important point is:
A FEDERAL PAYMENT-STABLECOIN FRAMEWORK HAS BEEN ENACTED, AND THE IMPLEMENTING RULES ARE NOW BEING BUILT.
That materially changes the strategic environment.
XIII. STABLECOINS ARE ONE RAIL — NOT THE SETTLEMENT ENGINE
This distinction is essential to REALATAR™. The Instant Settlement Engine™ should be rail-agnostic.
If a regulated bank payment is appropriate, use it.
If FedNow fits the transaction and amount, use FedNow.
If RTP fits, use RTP.
If a conventional wire is required, coordinate the wire.
If tokenized commercial-bank deposits mature into an appropriate institutional rail, support them.
If a legally permissible and appropriately regulated payment stablecoin becomes the superior rail for a particular transaction, use it.
Tokenized deposits deserve particular attention. HSBC describes its service as combining the familiarity and trust of traditional bank deposits with the speed, transparency and automation of blockchain rails — money that remains a regulated bank liability while moving 24/7. J.P. Morgan’s Kinexys is built on the same premise at a larger scale. For a family office settling a trophy asset, that combination of regulated money and programmable movement may prove more important than any single token.
THE PRODUCT SHOULD NOT BE A STABLECOIN.
THE PRODUCT SHOULD BE EXECUTABLE SETTLEMENT.
The rail can change. The ownership architecture survives. That is the same principle behind:
OWN THE RAILS. NOT THE MODEL.™
REALATAR™ should not become hostage to one blockchain, one AI model, one wallet provider, one payment network, one stablecoin or one bank. The intelligence layer should route toward the lawful rail best suited to the transaction.
XIV. PROJECT AGORÁ — THE FINANCIAL SYSTEM IS TESTING THE SAME IDEA
The most important external evidence for #172 may not come from real estate at all. It comes from the Bank for International Settlements.
In May 2026, the BIS Innovation Hub reported that Project Agorá’s prototype had demonstrated atomic cross-border wholesale settlement using tokenized commercial-bank deposits and tokenized central-bank reserves. The project brings together major central banks and more than 40 regulated private-sector financial institutions.
Atomic means:
ALL LEGS COMPLETE — OR NONE COMPLETE.
That matters because traditional multi-leg transactions create settlement risk during the interval between obligations. Project Agorá also demonstrated that compliance logic and conditional triggers could be embedded into programmable workflows.
Then the project moved further. In July 2026, 28 financial institutions and central banks — including the Bank of England, Bank of Japan and Swiss National Bank alongside J.P. Morgan, Citi and UBS — settled approximately CHF 800,000 in real value across 17 transaction scenarios and six currencies. The average settlement time was about 80 seconds.
This does not prove a Palm Beach house can be atomically deeded tomorrow. It proves something more useful:
ATOMIC, PROGRAMMABLE, CROSS-JURISDICTIONAL FINANCIAL SETTLEMENT IS NO LONGER MERELY A CRYPTOGRAPHIC THEORY.
Major monetary institutions are testing the architecture. And the BIS emphasizes the same things #172 must emphasize: legal finality, privacy, AML/CFT, sanctions, interoperability, operational resilience, governance and coexistence with existing financial systems.
That is not opposition to innovation. That is what institutional innovation looks like.
XV. ATOMIC REAL ESTATE SETTLEMENT™ — DEFINE IT PRECISELY
Atomicity is one of the most abused words in digital assets. So let me define what I mean.
For REALATAR™, Atomic Real Estate Settlement™ is the architectural objective of synchronizing the final legally permissible movement of value with the final legally operative transfer or updating of the relevant ownership rights, so that avoidable settlement exposure between the two is minimized.
That does not necessarily mean the legal deed itself exists as a token.
It does not mean a blockchain supersedes the county recorder.
It does not mean the smart contract decides property law.
And it does not mean every transaction will have identical mechanics.
The exact state transition will depend on jurisdiction. In one structure, finality may require deed recording. In another, the underlying property may remain owned by an LLC while membership interests change. In another, investors may acquire securities representing economic interests in an SPV. In another, beneficial rights may move while record title remains unchanged.
That is exactly why #169 and #170 had to come before #172.
YOU CANNOT ATOMICALLY SETTLE A RIGHT YOU HAVE NOT DEFINED.
YOU CANNOT PROGRAM A LEGALLY VALID TRANSFER UNTIL YOU KNOW WHICH LEGAL STATE MUST CHANGE.
XVI. THE INSTANT SETTLEMENT ENGINE™ — NINE OPERATING LAYERS
The architecture now becomes clear.
LAYER 1 — VERIFIED IDENTITY™. Establish the legitimate participants: people, entities, trusts, SPVs and authorized representatives.
LAYER 2 — VERIFIED AUTHORITY™. Establish who possesses the legal power to act. Identity alone is insufficient.
LAYER 3 — AUTHORITATIVE OWNERSHIP STATE™. Identify what is owned, by whom, through which structure and according to which authoritative record. This inherits directly from #169.
LAYER 4 — LEGAL CONTROL™. Identify jurisdiction, governing agreements, transfer restrictions, liens, conditions, regulatory limits and required legal instruments. This inherits directly from #170.
LAYER 5 — VERIFIED CAPITAL™. Establish financial capacity, financing, funding source where required, approvals and executable payment capability.
LAYER 6 — CONDITIONS-TO-CLOSE GRAPH™. Model every prerequisite. Determine responsibility. Track evidence. Resolve exceptions. Know what remains incomplete.
LAYER 7 — PROGRAMMABLE LIQUIDITY™. Select and prepare the appropriate regulated payment rail.
LAYER 8 — ATOMIC / COORDINATED EXECUTION™. When every required condition is satisfied, coordinate the final movement of money, rights and recording instructions as simultaneously as the applicable systems and law allow.
LAYER 9 — PROVENANCE™. Preserve the final transaction state, evidence package, chronology and content-integrity proofs.
This is much more powerful than:
BUY → SELL → CLOSE.
XVII. THE REALATAR™ CONTROL PLANE
REALATAR™ should not attempt to become every institution inside the transaction. That would be the wrong architecture. REALATAR™ should become the control plane coordinating the institutions, systems and states required to move the transaction forward.
Think of air traffic control.
The tower does not manufacture the aircraft.
It does not own every airline.
It does not build the runway.
It does not refine the jet fuel.
It does not own the passenger.
But it coordinates state, sequence, authorization and movement.
That is increasingly how I see REALATAR™.
Not another title company.
Not another lender.
Not another portal.
Not another stablecoin.
Not another CRM.
Not another brokerage.
Not another blockchain.
THE ORCHESTRATION LAYER ACROSS THEM.
REALATAR’s current public architecture already connects identity, property, intelligence, capital, provenance, settlement and liquidity, and describes T-0 as a strategic direction. #172 gives that settlement ambition a more rigorous institutional definition.
XVIII. PROTECT NECESSARY INTERMEDIARIES. DELETE UNNECESSARY INTERMEDIATION.
This is where I want to refine some of my own earlier language. It is tempting, when confronting an inefficient legacy system, to say, “Delete every intermediary.” That is too crude. The better principle is:
DELETE UNNECESSARY INTERMEDIATION.
PRESERVE NECESSARY RISK CONTROL.
AUTOMATE WHAT CAN RESPONSIBLY BE AUTOMATED.™
A title professional who discovers an undisclosed heir is not friction. That person is protecting ownership integrity.
An attorney who identifies that an entity lacks authority to sell is not friction. That attorney is preventing a defective transfer.
A lender performing legally required underwriting is not merely slowing the transaction.
A disclosure period mandated to protect the borrower is not obsolete architecture.
But:
Re-keying the same verified customer information four times? Avoidable.
Emailing a PDF because two systems cannot communicate? Avoidable.
Waiting until Monday because an internal system cannot process a technically permissible weekend transaction? Potentially avoidable.
Manually reconciling a payment already cryptographically or institutionally confirmed? Potentially avoidable.
Calling five people to determine which condition remains incomplete? Avoidable.
THE TARGET IS NOT PEOPLE.
THE TARGET IS FRICTION.
That distinction matters commercially. It also makes REALATAR™ a potential partner to high-performing professionals rather than an ideological threat to them.
XIX. WHAT THIS MEANS FOR THE BROKER, AGENT OR DEVELOPER™
You do not need to become a blockchain engineer. You do not need to write smart contracts, operate an eVault or understand every payment-settlement protocol. Your client does not hire you to do those things.
The operational advantage is simpler. Imagine knowing earlier:
Is this buyer real?
Can they perform?
Who is authorized to sign?
Which title issue remains unresolved?
Which document is missing?
Which regulatory condition has not been satisfied?
Is financing complete?
Are funds ready?
Is recording ready?
What is preventing settlement right now?
Instead of spending the final week chasing everybody:
THE TRANSACTION TELLS YOU WHAT IS NOT READY.
That improves the professional. It does not eliminate the professional.
For the broker or agent: less administrative chase, better client visibility, earlier detection of weak buyers, fewer surprises, more confidence around closing — and more time devoted to advice, negotiation and relationships.
For the developer: repeatable buyer qualification, portfolio-level transaction visibility, better capital and treasury planning, and less closing uncertainty across units.
For the client: a more transparent journey.
THE BEST TECHNOLOGY SHOULD MAKE THE TRUSTED PROFESSIONAL MORE VALUABLE BY MAKING LOW-VALUE ADMINISTRATION LESS NECESSARY.
That becomes a permanent Agent/Broker Operational Advantage™ principle across future Ledger entries.
XX. WHAT THIS MEANS FOR UHNWIs AND FAMILY OFFICES
For a family office, billionaire, institutional owner or global investor, the problem changes again. At scale, time itself becomes capital.
A single transaction can involve multiple jurisdictions, entities, trusts, tax counsel, private banks, currency conversion, cross-border compliance, legal authority, wealth structuring, lenders, investment committees and multiple beneficial owners. For a family enterprise, it can also touch succession planning, board governance and the rising generation who will one day inherit both the real assets and the process that governs them.
The objective cannot simply be, “Make everything instant.” The objective is:
MAKE EVERYTHING KNOWABLE.
THEN MAKE EVERYTHING EXECUTABLE AS SOON AS IT IS LEGALLY READY.
That is a much more sophisticated proposition. For institutional capital, visibility may be as valuable as raw speed.
Knowing exactly which condition prevents execution can improve treasury planning.
Knowing whether capital needs to remain reserved can improve liquidity management.
Knowing that identity has already been appropriately verified can reduce duplication.
Knowing precisely which legal right is being transferred reduces ambiguity.
Knowing the evidentiary state of the transaction improves governance.
SPEED IS THE BENEFIT.
CONTROL IS THE INSTITUTIONAL PRODUCT.
XXI. FROM LOCAL CLOSING TO GLOBAL SETTLEMENT
Entry #171 established the global distribution problem. #172 exposes what happens once that strategy succeeds.
A buyer in Singapore discovers a Miami property.
A London family office evaluates Palm Beach.
Dubai capital considers Manhattan.
An Australian owner transacts with a U.S. buyer.
The information can already move globally. The capital may move globally. But property law remains local.
Tax remains jurisdictional.
Sanctions rules remain jurisdictional.
Banking rules remain jurisdictional.
Foreign-investment restrictions may apply.
Entity law matters.
Recording law matters.
Notarial requirements matter.
That is why I do not define programmable settlement as borderless law.
GLOBAL CAPITAL.
LOCAL LAW.
INTEROPERABLE INFRASTRUCTURE.™
REALATAR™ should make the layers interoperable without pretending the layers disappear. That is what institutional-grade Web3 should have been about from the beginning.
XXII. THE SETTLEMENT ENGINE SHOULD BE MODEL-AGNOSTIC AND RAIL-AGNOSTIC
The AI model will change.
The blockchain may change.
Payment technologies will change.
Banks will change their APIs.
Identity standards will evolve.
Regulators will change requirements.
The settlement engine has to survive all of them. That means the architecture should separate the transaction state from the vendor implementing one function inside that state.
If AI model A is best for document extraction today and model B is better next year, change the model.
If payment rail A is faster but rail B offers better finality for a particular jurisdiction, select B.
If one chain ceases to meet legal, technical or economic requirements, migrate.
If a county introduces direct API-based recording, connect it.
If a title institution provides a better authoritative data feed, integrate it.
THE CONTRACTUAL AND OWNERSHIP STATE IS THE CONSTANT.
THE TECHNOLOGY IMPLEMENTING IT IS VARIABLE.
That is sovereignty at the infrastructure layer — and it is the operating logic of Entry #158. Bain’s 2025 Technology Report estimated that AI’s compute demand is growing at more than twice the rate of Moore’s Law and that about $2 trillion in annual revenue would be needed by 2030 to fund the required data-center buildout. When the underlying technology moves that fast, the enterprise that owns the state survives the upgrade cycle. The enterprise that owns only the tool inherits its depreciation.
XXIII. THE STEVE JOBS TEST: COMPLEXITY UNDERNEATH, SIMPLICITY ABOVE
The settlement stack I have just described is complex. That is not a weakness. Aircraft are complex. Payment systems are complex. Semiconductor fabs are complex. The electrical grid is complex.
The problem occurs when the customer is forced to experience the full complexity of the infrastructure underneath the product. This is where Steve Jobs remains one of my enduring reference points. The user should not have to understand the architecture to benefit from it.
The buyer should see:
Identity verified.
Funds verified.
Title ready.
Documents ready.
Two conditions remaining.
Settlement ready.
Not twenty-seven portals, ninety-four email threads, sixteen incompatible PDFs, seven login credentials and one last-minute phone call asking whether the wire arrived.
SOPHISTICATED INFRASTRUCTURE SHOULD PRODUCE SIMPLE EXPERIENCE.
That is the Jobs discipline applied to closing.
XXIV. THE ELON MUSK TEST: DELETE BEFORE YOU AUTOMATE
The 2026 SpaceX materials I studied framed a repeatable operating model around first-principles thinking: make requirements less wrong, delete unneeded process steps, optimize, accelerate — and only then automate. That order matters. Automating a bad process merely makes the bad process execute faster.
The settlement translation is:
↓
IDENTIFY THE RISK IT PROTECTS
↓
REMOVE DUPLICATION
↓
INTEGRATE THE DATA
↓
VERIFY ONCE
↓
OPTIMIZE
↓
ACCELERATE
↓
AUTOMATE THE PERMITTED STATE TRANSITION
↓
SETTLE
The most valuable first-principles question in real estate may therefore be:
IF WE WERE DESIGNING PROPERTY SETTLEMENT FOR THE FIRST TIME IN 2026, WHICH PARTS OF THE CURRENT CLOSING WOULD WE DELIBERATELY REBUILD EXACTLY AS THEY ARE?
Some.
Not all.
That gap is the opportunity.
XXV. THE MASAYOSHI SON TEST: BUILD THE GOOSE
Entry #171 revived one of the ideas I have admired for years. Masayoshi Son’s 2026 SoftBank presentation put the principle simply: what matters is not merely the eggs. It is the goose — the productive system capable of continuing to create value.
#172 extends the framework:
A FASTER CLOSING IS AN EGG.
A REUSABLE SETTLEMENT ARCHITECTURE IS THE GOOSE.™
The objective is not to engineer one transaction that closes quickly. It is to create infrastructure that learns how thousands — and eventually millions — of future transactions can move with less unnecessary friction.
One identity verification can become reusable where law and consent permit.
One property record can become an evolving ownership graph.
One transaction can enrich future provenance.
One resolved title condition can improve asset intelligence.
One participant’s permissions can persist.
One closing can strengthen the system that supports the next.
That is compounding infrastructure.
THE DEEPER VALUE IS NOT THE CLOSING.
IT IS THE SYSTEM THAT MAKES FUTURE CLOSINGS BETTER.
XXVI. THE SETTLEMENT FLYWHEEL™
A transaction should improve the infrastructure that enabled it. The flywheel becomes:
The closing is no longer the end. It is one state transition in a continuing ownership lifecycle. That is how #172 begins preparing the ground for the next architecture:
FROM CLOSING TO COMPOUNDING™
XXVII. WHY WIRE FRAUD MAKES ATOMICITY MORE IMPORTANT — AND MORE DANGEROUS
Large transaction values attract fraud, and ALTA’s 2026 findings show the attack moving toward the payment instruction itself: spoofed contacts, deepfaked voices and pressure to move funds before verification. Title firms reported that sellers avoiding meetings or calls, and demands for mail-away signings with their own notaries, were among the most common red flags.
That exposes an important distinction. The danger does not come from digital money itself. It comes from an information and authorization gap between who should receive the money and where the payment instruction actually points.
Atomic settlement can reduce the period during which one side has performed while the other has not. It can reduce reconciliation and some manual handoffs. But atomicity does not magically know that the recipient is legitimate. Therefore:
IDENTITY BEFORE INSTRUCTION.
AUTHORITY BEFORE EXECUTION.
VERIFICATION BEFORE VELOCITY.™
That order is non-negotiable.
XXVIII. WHAT ATOMIC SETTLEMENT DOES NOT SOLVE
This may be one of the most important sections in the report, because institutional trust comes partly from stating what the technology cannot do.
Atomic settlement does not automatically discover forged source documents.
It does not resolve a previously unknown heir.
It does not decide whether a deed was procured by coercion.
It does not guarantee an appraiser was correct.
It does not determine whether a corporation’s board authorization was legally sufficient unless the appropriate evidence and rules are incorporated.
It does not substitute for sanctions screening.
It does not replace tax law.
It does not establish zoning rights.
It does not cure title merely because a token exists.
It does not make a fraudulent identity legitimate.
It does not turn an unlawful transaction into a lawful one.
And it does not cause a county recorder to recognize a transfer method the jurisdiction does not accept.
Atomicity addresses the execution gap. The rest of The Sovereign Transaction Quad™ exists precisely because settlement depends on truth and law.
XXIX. THE $625 TRILLION SETTLEMENT QUESTION
Statista Market Insights estimates the worldwide real estate market at approximately $624.62 trillion in 2026, including approximately $506.73 trillion of residential real estate. Savills separately measured global real estate value at approximately $393.3 trillion at the start of 2025, using a different methodology.
As I have established throughout The Sovereign Ledger™, those estimates should not be blended. Different methodology. Different definitions. Different dates. Different coverage. But both make the same strategic point: this is an enormous asset class, and enormous asset classes require enormous infrastructure.
So #172 asks:
WHAT IS THE ECONOMIC VALUE OF REMOVING ONE DAY OF AVOIDABLE SETTLEMENT LATENCY FROM EVEN A SMALL FRACTION OF GLOBAL REAL ESTATE FLOW?
What is the value of reducing duplicate verification?
What is the value of fewer failed handoffs?
What is the value of stronger fraud protection?
What is the value of better capital visibility?
What is the value of reusable identity?
What is the value of lower reconciliation expense?
What is the value of knowing exactly what prevents closing?
What is the value of settling the instant the transaction is truly ready?
Those are infrastructure questions.
XXX. CAPITAL VELOCITY WITHOUT HYPE
I have previously explored capital velocity aggressively. #172 requires a more precise treatment.
If a transaction closes faster, capital may become available sooner. That can matter economically. But settlement time does not mechanically translate into a fixed number of additional annual investments. Capital redeployment depends on deal availability, investment mandates, risk appetite, tax, liquidity needs, due diligence, portfolio allocation, financing and the characteristics of the next opportunity.
Therefore I will not claim, “T-0 makes the same capital transact twelve times per year.” That would confuse theoretical availability with actual investment behavior. The institutionally defensible principle is:
LOWER SETTLEMENT LATENCY INCREASES OPTIONALITY.
Optionality has value. A family office that receives proceeds today possesses choices that a family office awaiting proceeds for another two weeks does not. A developer with faster visibility into receivables can plan differently. A lender with better certainty can manage liquidity differently. A seller can redeploy capital earlier.
VELOCITY DOES NOT GUARANTEE RETURN.
IT CREATES THE OPTION TO ACT SOONER.
That is the economic thesis.
XXXI. FROM DISTRIBUTION EFFICIENCY TO SETTLEMENT EFFICIENCY
Entry #171 introduced Strategic Return on Attention™. #172 now gives it a transaction counterpart. I define Settlement Efficiency™ as the relationship among:
The fastest closing is not necessarily the best closing.
The cheapest closing is not necessarily the best closing.
The closing with the fewest people is not necessarily the best closing.
The best architecture optimizes total outcome.
That means measuring:
Time-to-Verified-Counterparty — how quickly can both sides be confidently established?
Time-to-Title-Ready — how quickly can authoritative rights and material exceptions be identified and resolved?
Time-to-Capital-Ready — when is funding actually executable?
Condition Resolution Time — how long does each unresolved prerequisite remain open?
Final Settlement Latency — once all conditions are true, how long until legal and economic completion?
Exception Rate — how often does execution fail because a supposedly satisfied condition was wrong?
Reconciliation Load — how much manual work is required after execution?
Fraud Loss / Near-Miss Rate — does faster execution remain safe?
Post-Close Correction Rate — how often must records be repaired?
That is how REALATAR™ should eventually prove its value. Not by saying, “Blockchain is faster.” By demonstrating:
THIS ARCHITECTURE REDUCED X HOURS, Y HANDOFFS, Z EXCEPTIONS AND N DOLLARS OF AVOIDABLE COST WITHOUT INCREASING LOSS OR LEGAL RISK.
That is institutional proof.
XXXII. THE SETTLEMENT CONTROL PLANE™
I now see REALATAR™ as coordinating four classes of information simultaneously.
THE OWNERSHIP STATE — who owns what?
THE LEGAL STATE — what must legally happen?
THE TRANSACTION STATE — which conditions are satisfied?
THE CAPITAL STATE — is value ready to move?
When all four align, execution becomes possible.
YES + YES + YES + YES
=
SETTLEMENT READY™
That can eventually become a visual control panel rather than a philosophy.
XXXIII. FROM AI THAT ANSWERS TO AI THAT ORCHESTRATES
The first generation of generative AI answered questions. The next generation increasingly performs work across systems. IDC expects agentic AI to drive worldwide AI spending to $1.3 trillion in 2029. That evolution matters enormously to settlement.
REALATAR™ should not use AI merely to write a prettier property description. An intelligent settlement architecture could help classify transaction documents, extract required conditions, compare versions, identify missing data, surface title exceptions, route work to responsible parties, monitor deadlines, detect anomalies, match records, summarize unresolved issues, prepare decision-support material and coordinate permitted workflows.
But the institutions deploying AI are learning where the guardrails belong. Bain’s 2025 Technology Report found that most companies remain in experimentation mode with agentic AI before taking their “hands off the wheel.” Forrester predicted that an agentic AI deployment would cause a publicly disclosed breach in 2026, and its AEGIS guardrail framework puts identity and access management and data provenance at the center of agent security.
Those findings do not argue against AI in settlement. They argue for putting AI in the right seat:
AI SHOULD ASSIST STATE DETERMINATION.
AUTHORITATIVE SYSTEMS AND AUTHORIZED HUMANS SHOULD DETERMINE LEGAL FINALITY WHERE REQUIRED.
The model can reason.
The law governs.
The institution executes.
The ledger records.
XXXIV. THE OWNER SHOULD SEE THE TRANSACTION, NOT CHASE IT
Customer experience is the forgotten half of settlement innovation. Imagine the seller asking, “Where are we?” Today, the answer may require several calls. In the future, the answer should resemble:
EXHIBIT D — THE OWNER’S VIEW (ILLUSTRATIVE)
| Counterparty | VERIFIED |
| Authority | VERIFIED |
| Title | READY — 1 exception resolved |
| Financing | APPROVED |
| Disclosure period | COMPLETE |
| Funds | READY |
| Execution documents | COMPLETE |
| Recording | READY |
| Settlement status | ENABLED |
The owner should not have to ask six institutions to reconstruct that answer.
TRANSACTION VISIBILITY IS PART OF OWNERSHIP CONTROL.
This is where my Touchpoint customer-journey thinking returns. At Touchpoint Entertainment, I was focused on mapping every customer touchpoint. In 2026, the touchpoint becomes a transaction state. Different industry. Same operating discipline.
XXXV. THE BROKERAGE BRIDGE™
The Sovereign Ledger™ needs to remain accessible to the very industry it is attempting to educate. So here is the simple version.
FOR THE BROKER — know earlier whether your buyer is real and ready.
FOR THE AGENT — spend less time chasing administrative status.
FOR THE DEVELOPER — see portfolio-level closing readiness.
FOR THE SELLER — understand exactly what is blocking completion.
FOR THE BUYER — receive greater transparency and fewer last-minute surprises.
FOR THE TITLE PROFESSIONAL — receive better-organized information and reduce avoidable duplicate handling.
FOR THE ATTORNEY — focus human judgment on substantive legal issues rather than administrative information retrieval.
FOR THE LENDER — gain better visibility into transaction readiness and required conditions.
FOR THE FAMILY OFFICE — coordinate identity, authority, capital and legal structures across a more coherent workflow.
Nobody needs to understand the blockchain underneath the engine. They need to experience:
LESS FRICTION.
MORE VISIBILITY.
BETTER CONTROL.
FASTER EXECUTION WHEN READY.
XXXVI. THE ARCHITECTURE SHOULD NEVER MAKE FRAUD IRREVERSIBLE FASTER
This principle deserves its own section. Digital finance often celebrates irreversibility. Real estate should be more nuanced.
An irreversible transaction is wonderful when the transaction is valid. An irreversible fraudulent transaction is catastrophic. Therefore the architecture needs staged certainty:
Identity certainty → Authority certainty → Asset certainty → Capital certainty → Condition certainty → Execution certainty
FINALITY SHOULD BE THE REWARD FOR VERIFICATION — NOT A SUBSTITUTE FOR IT.™
That sentence belongs at the heart of REALATAR™.
XXXVII. THE OWNERSHIP VALUE CHAIN™ IS NOW BECOMING COMPLETE
Across #169–#172, the larger architecture becomes increasingly visible.
Each step answers a different question.
What is the asset?
What do we know about it?
Who needs to understand it?
Who should see it?
Who is genuinely interested?
Who are they?
Can they act?
Can they perform?
What law governs?
What remains unresolved?
Can we execute?
Who owns it now?
Can we prove the chronology?
What options exist next?
Where does the capital go from here?
In Entry #168, The 7,000-Year War for the Ledger™, I traced how every era of money, property and power has turned on one question: who controls the ledger? Settlement is where that question stops being historical and becomes operational — because settlement is the moment the ledger changes.
This is why I no longer view REALATAR™ as simply a real estate technology platform.
THE AMBITION IS AN OWNERSHIP OPERATING SYSTEM.
XXXVIII. THE GOAL IS NOT DISINTERMEDIATION. IT IS JUSTIFIED INTERMEDIATION.
Every intermediary should answer one question:
WHAT VALUE OR RISK CONTROL DO YOU ADD?
If an intermediary prevents fraud, protects legal rights, provides trusted judgment, supplies capital, guarantees an obligation, underwrites risk or creates genuine distribution value, that function may deserve to remain.
If the function is moving the same information between two incompatible systems, requesting data already verified elsewhere, waiting for somebody to manually reconcile information the systems could reconcile automatically, or charging because the architecture has no alternative path — then innovation has a target.
This is a much more powerful thesis than “middlemen are bad.” Middlemen are not the issue.
UNJUSTIFIED FRICTION IS THE ISSUE.
That is the economic doctrine #172 establishes permanently.
XXXIX. THE 2026 PROOF POINTS
The pieces are already visible.
Average purchase-mortgage closing time reached a record-fast 36.8 days in ICE’s March 2026 data.
The MERS eRegistry surpassed 3 million eNotes in March 2026.
Remote online notarization has legal or executive-order pathways across nearly every state, although requirements differ.
FedNow and RTP both support near-real-time settlement around the clock, now for payments up to $10 million.
The GENIUS Act has established a statutory framework for U.S. payment stablecoins, with implementation continuing toward its expected January 18, 2027 effective date.
Project Agorá has demonstrated cross-border atomic settlement using tokenized bank money and central-bank reserves, and has conducted controlled real-value testing.
At the same time, seller-impersonation attempts have more than doubled since 2024 — demonstrating why identity verification must strengthen as transaction velocity rises.
Different systems.
Different institutions.
Different legal contexts.
But the direction is clear:
IDENTITY IS BECOMING DIGITAL.
DOCUMENTS ARE BECOMING DIGITAL.
MONEY IS BECOMING INSTANT.
FINANCIAL ASSETS ARE BECOMING PROGRAMMABLE.
RECORDING IS BECOMING ELECTRONIC.
The missing piece is orchestration.
THAT IS THE SETTLEMENT ENGINE.
XL. THE COST OF WAITING
Every infrastructure shift has a period when the new rails exist but most of the market has not yet reorganized around them. The organizations that study the architecture early help define the standards everyone else later works within.
Real estate settlement is entering that period now. The payment rails are live. The eNote registry is live. The atomic-settlement prototypes are being tested with real money by the institutions that will eventually be asked to connect to property transactions. The regulatory framework for payment stablecoins takes effect in less than four months.
For a brokerage, the cost of waiting is being the last firm in the market still telling clients to “hang tight” while its competitors show a live readiness dashboard. For a developer, it is capital held in suspense across a hundred units. For a family office, it is liquidity that cannot be redeployed while an avoidable handoff completes. None of that shows up as a line item. All of it shows up in the outcome.
THE RAILS WILL NOT WAIT FOR THE INDUSTRY TO BE READY.
THE INDUSTRY WILL BE ASKED TO BE READY FOR THE RAILS.
XLI. THE FOUR-ENTRY DOCTRINE
We can now express #169–#172 in four sentences.
#169 — KNOW WHAT IS TRUE.
#170 — KNOW WHAT LEGALLY CONTROLS.
#171 — FIND THE RIGHT CAPITAL.
#172 — EXECUTE WHEN EVERYTHING IS READY.
TRUTH → LAW → DEMAND → EXECUTION™
And underneath all four:
PROOF.
Because without evidence, truth becomes assertion, law becomes interpretation, demand becomes marketing and execution becomes risk.
XLII. THE FIVE INSTITUTIONAL DOORS STILL HOLD
This settlement architecture fits directly into the institutional architecture established around my work.
WHO I AM — experience and operating history.
HOW I THINK — The Sovereign Ledger™.
WHAT I AM BUILDING — REALATAR™.
HOW I PROVE IT — provenance.
HOW I REACH THE MARKET — The Global Distribution Control Layer™.
And now #172 begins connecting those doors operationally. Distribution produces opportunity. REALATAR™ converts opportunity into workflow. The Ledger supplies the intelligence. Provenance supplies evidence. Experience supplies judgment.
FROM ATTENTION TO OWNERSHIP™
BECOMES EXECUTABLE.
XLIII. THE $625 TRILLION QUESTION HAS CHANGED AGAIN
Entry #171 asked: how does the local asset reach global capital? Entry #172 asks:
WHAT HAPPENS WHEN THE GLOBAL CAPITAL SAYS YES?
That may be the more important question. A market does not become more liquid merely because more people can see it. It becomes more liquid when participants trust what they see, counterparties can be verified, rights can be established, capital can move, conditions can be satisfied and ownership can actually change hands.
Distribution creates optionality.
Settlement converts optionality into economic reality.
ATTENTION CREATES THE POSSIBILITY.
SETTLEMENT CREATES THE OWNERSHIP.
XLIV. THE NEXT GENERATION OF REAL ESTATE INFRASTRUCTURE
I believe the next generation of real estate infrastructure will increasingly need to be:
GLOBAL IN DISCOVERY — because capital is global.
LOCAL IN LAW — because property remains jurisdictional.
PERSISTENT IN IDENTITY — because repeated verification creates unnecessary friction.
AUTHORITATIVE IN OWNERSHIP — because conflicting records destroy confidence.
PROGRAMMABLE IN WORKFLOW — because conditional state can increasingly be machine-coordinated.
INTEROPERABLE IN PAYMENTS — because no single settlement rail will serve every market.
HUMAN-GOVERNED WHERE JUDGMENT MATTERS — because legal and fiduciary accountability cannot simply be delegated to code.
CRYPTOGRAPHIC IN PROVENANCE — because independently inspectable chronology creates valuable evidence.
MODEL-AGNOSTIC IN AI — because today’s best model will not be tomorrow’s.
And:
ATOMIC WHERE FINAL EXECUTION CAN LEGALLY AND TECHNICALLY BE MADE ATOMIC.
That is the standard.
XLV. THE REALATAR™ SETTLEMENT DOCTRINE
I now lock the following as the permanent settlement doctrine:
VERIFY BEFORE VELOCITY.™
PROTECT NECESSARY FRICTION. ELIMINATE AVOIDABLE FRICTION.™
T-0 DOES NOT MEAN ZERO DILIGENCE. IT MEANS ZERO AVOIDABLE LATENCY AFTER DILIGENCE IS COMPLETE.™
FINALITY SHOULD BE THE REWARD FOR VERIFICATION — NOT A SUBSTITUTE FOR IT.™
VALUE MOVES WHEN OWNERSHIP IS READY TO MOVE. OWNERSHIP MOVES WHEN VALUE IS READY TO MOVE.™
And ultimately:
Verify once.
Satisfy the conditions.
Settle once.
Prove forever.™
That is The Instant Settlement Engine™ in four lines.
SUMMARY
Entry #172 closes a major architectural gap. #169 established The Authoritative Ownership Record™. #170 established The Legal Control Layer™. #171 established The Global Distribution Control Layer™. Now #172 establishes The Instant Settlement Engine™.
TRUTH → LAW → DEMAND → EXECUTION™
The settlement problem is not simply that real estate is slow. The more important problem is that transaction readiness remains fragmented across identity systems, title records, legal structures, lenders, payment systems, documents, professionals, regulators and recording infrastructure.
That fragmentation creates a Real Estate Friction Budget™ of time, information, capital, intermediary and risk friction. Some should disappear. Some should be protected. The distinction is the architecture.
The Verified Counterparty Rail™ establishes who is participating and whether they possess the identity, authority, eligibility and capacity required to transact. The Conditions-to-Close Graph™ converts closing from a folder of documents into an observable set of transaction states. Programmable Liquidity™ prepares the appropriate lawful payment rail. Atomic Real Estate Settlement™ seeks to synchronize the final movement of value with the legally relevant transfer or updating of ownership rights. Provenance preserves the record.
None of this requires declaring war on brokers, title professionals, banks, attorneys or regulators. The opposite. The best professionals become more valuable when technology removes the administrative waste surrounding the high-value judgment they provide.
THE TARGET IS NOT THE INTERMEDIARY.
THE TARGET IS UNNECESSARY INTERMEDIATION.
At the same time, fraud is increasing — making stronger identity, authority and verification even more important. The conclusion is not, “Move everything faster.” The conclusion is:
KNOW EVERYTHING REQUIRED TO MOVE — THEN MOVE IT WITH AS LITTLE AVOIDABLE LATENCY AS POSSIBLE.
That is a very different standard.
TO RECAP
Real estate has spent decades digitizing pieces of the closing.
The listing became digital.
The mortgage application became digital.
The signature became digital.
The note became digital.
The bank payment became instant.
The recorder increasingly accepts electronic documents.
The identity system is becoming digital.
Capital is becoming programmable.
And AI can increasingly observe and coordinate the workflow between them.
Yet the transaction still behaves too often as though those components live in separate centuries. That is the opportunity. The next breakthrough is not another isolated digital feature.
IT IS ORCHESTRATION.
The right buyer, the money, the legal right and the payment rail may all already exist. The missing layer is the intelligence capable of understanding what is ready, what is not, what must happen next, who is authorized to do it — and:
WHEN THE ENTIRE TRANSACTION IS ACTUALLY READY TO SETTLE.
#171 FINDS THE CAPITAL.
#172 MAKES THE CAPITAL EXECUTABLE.™
I do not define instant settlement as reckless speed. I define it as earned velocity — earned because every necessary condition has been satisfied.
T-0 IS NOT THE BEGINNING OF THE TRANSACTION.
T-0 IS THE MOMENT EVERYTHING BEFORE IT BECOMES TRUE.™
Once that moment arrives: why wait?
SYNTHESIS
Entry #172 completes the operational transition from agreement to value by defining the architectural mechanics of atomic real estate settlement. By treating transactions as observable control planes rather than unstructured document folders, the system converts complex closing cycles into machine-readable dependencies.
The stack attacks time, information, capital and intermediary friction while optimizing risk friction. Faster settlement without rigorous counterparty verification merely accelerates fraud. With ALTA’s September 2026 study showing 59% of surveyed title firms encountering seller-impersonation attempts, verification before velocity is non-negotiable.
Programmable Liquidity™ is designed to be rail-agnostic. FedNow, RTP, a wire, tokenized deposits, a regulated payment stablecoin once the GENIUS Act is in force or, longer term, tokenized-reserve settlement of the kind tested in Project Agorá — the engine routes value toward the most suitable lawful rail.
EXHIBIT F — THE NINE-LAYER SETTLEMENT ENGINE STACK
| Layer | Function |
|---|---|
| 1. Verified Identity™ | Natural persons, beneficial owners, entities, trusts and SPVs |
| 2. Verified Authority™ | Legal power and binding execution capacity |
| 3. Authoritative Ownership State™ | Which record controls the right being transferred (inherits #169) |
| 4. Legal Control™ | Jurisdiction, covenants, liens and required instruments (inherits #170) |
| 5. Verified Capital™ | Proof of funds, financing, source-of-funds and AML compliance |
| 6. Conditions-to-Close Graph™ | Observable tracking of every prerequisite state |
| 7. Programmable Liquidity™ | Multi-rail routing: FedNow, RTP, wire, tokenized deposits, regulated stablecoins |
| 8. Atomic / Coordinated Execution™ | Synchronizing funds and ownership-state instructions as far as law and systems allow |
| 9. Provenance™ | Evidence package and SHA-256 · OpenTimestamps · Bitcoin-anchored chronology |
REALATAR™ serves as the orchestration control plane. It does not displace necessary brokers, attorneys or title professionals; it targets unnecessary intermediation while strengthening human judgment. The architecture turns settlement latency into institutional optionality.
MY BOTTOM LINE
The global real estate market — approximately $624.62 trillion in 2026 by Statista’s estimate — has spent two decades digitizing isolated, vertical fragments. The listing became a web portal. The signature became an e-signature. The promissory note became an eNote. The wire became an instant bank transfer. Yet transactions still operate as though these systems were built in different centuries.
The real opportunity is not another digital feature. It is cross-stack orchestration. Entry #171 finds the capital. Entry #172 makes that capital executable the moment the transaction is truly ready.
I define instant settlement as earned velocity — velocity earned through identity, authority, title clarity, legal certainty and satisfied prerequisites. When every legal and financial condition on the control plane reports TRUE, capital and title should not sit in administrative suspense for weeks for reasons that no longer protect anyone. Where time protects a party, it stays. Where it merely reflects disconnected systems, it becomes the target.
=
SETTLEMENT ENABLED™
We do not design systems to automate uncertainty. We resolve uncertainty, align the law, verify the counterparties, execute as atomically as law and systems permit — and anchor the evidence of what happened to the Bitcoin blockchain, so the chronology can be inspected by anyone, indefinitely.
Verify once. Satisfy the conditions. Settle once. Prove forever.™ 🇺🇸
One institution. Four destinations. One Sovereign Architecture.
I have spent decades building an integrated infrastructure designed for absolute ownership:
WHO I AMhttps://geoffdeweaver.com
Identity. Experience. Trust.
PROVEN SCALE & TRACK RECORDhttps://geoffdeweaver.com/about-geoff-de-weaver/
Execution. Reach. Scale.
HOW I THINKhttps://geoffdeweaver.com/the-sovereign-ledger/
Intelligence. Evidence. Provenance.
WHAT I’M BUILDINGhttps://geoffdeweaver.com/realatar/
Ownership. Infrastructure. Execution.
IDENTITY. SCALE. INTELLIGENCE. INFRASTRUCTURE. 🇺🇸
Driven by the LIMITLESS doctrine:
OWN IT → PROTECT IT → PROVE IT → CONTROL IT → MULTIPLY IT → COMPOUND IT.
AI scales leverage. Blockchain secures provenance. Evidence establishes trust. Human authority guarantees sovereignty. Better products build the moat.
Who I Am commands attention.
My Track Record validates scale.
How I Think cements trust.
What I’m Building drives adoption.
This is the architecture.
INSTITUTIONAL METRICS · ENTRY #172
THE SOVEREIGN ARCHITECTURE · CORPUS RECORD AT PUBLICATION · SEPTEMBER 25, 2026 (ET)
172 Bitcoin-Anchored Entries · 2.62M+ Verified Words · 260+ Audiobook-Equivalent Hours · 800+ Strategic Blueprints
1.55B+ Reported Global Network / Reach Footprint · SHA-256 · OpenTimestamps · Bitcoin-Anchored Provenance
Methodology: 10,000 verified words ≈ one audiobook-equivalent hour (≈166.7 WPM). Methodology & Proof → Provenance™
~$625T Global Real Estate Market — Statista Market Insights 2026 estimate
The approximately $625 trillion figure is an estimated asset-market value under Statista’s methodology, not annual transaction volume. Savills’ separate $393.3 trillion estimate uses different definitions and methodology and is retained separately. Audiobook-Equivalent Hours are derived from the written corpus at 10,000 narrated words per hour (about 167 words per minute), rounded down to the nearest ten. The 1.55B+ figure is a reported global network/reach construct and is not an audited audience, unique-person count or measure of engagement. OpenTimestamps and Bitcoin anchoring provide evidence of chronology and content integrity for anchored entry states; cryptographic timestamping does not independently establish the factual truth of the underlying claims.
RESEARCH & METHODOLOGY STANDARD
This Entry distinguishes among current operating infrastructure, enacted legislation, proposed regulation, demonstrated prototypes, analyst forecasts and long-term architecture.
FedNow and RTP are functioning instant-payment infrastructures today. They do not independently provide atomic real estate title settlement. HSBC’s Tokenized Deposit Service and J.P. Morgan’s Kinexys are operating institutional payment services for eligible clients; they are not real estate settlement systems.
The GENIUS Act is enacted U.S. law, but as of September 2026 its implementation remains underway and it is expected to take effect on January 18, 2027.
Project Agorá has demonstrated atomic multi-currency wholesale settlement and conducted controlled real-value testing, but it is a wholesale-payment experiment — not a production real estate title network.
MERS eNotes, eClosing, eRecording and remote notarization demonstrate substantial digitization of the U.S. mortgage and closing stack, but do not mean every property transaction or jurisdiction supports fully electronic settlement.
McKinsey, BCG, Deloitte and IDC figures are forecasts with different scopes and dates; they are presented separately and are not combined. PwC, Accenture, Bain and Forrester findings are cited for what they measured or predicted, not extended beyond it.
REALATAR™ and The Instant Settlement Engine™ are therefore presented as an architecture and development objective: an orchestration system designed to reduce avoidable friction and move toward T-0 execution where legal, technical, regulatory and institutional conditions permit.
Evidence before assertion.
Architecture before scale.
Verification before velocity.
PRIVATE CAPITAL · STRATEGIC PARTNERSHIPS · INSTITUTIONAL ACCESS
For qualified discussions involving REALATAR™, ownership infrastructure, global distribution, strategic real estate, settlement architecture and capital partnerships:
BITCOIN · BLOCKCHAIN · OPENTIMESTAMPS PROVENANCE
Entry #172 is anchored the same way as every Entry in The Sovereign Ledger™. A canonical fingerprint of this Entry is hashed with SHA-256 — the same cryptographic hash function that secures the Bitcoin blockchain — and that hash is submitted through OpenTimestamps, an open-source protocol that aggregates many hashes and commits them into a Bitcoin transaction.
Once the commitment is confirmed in a Bitcoin block, anyone can independently verify — without trusting me, a website or any intermediary — that this exact fingerprint existed at or before that block’s time and has not been altered since. Change a single character and the hash no longer matches.
That is Layer 9 of the engine this Entry describes, applied to the Entry itself: provenance as the final state of every transaction. The Bitcoin blockchain supplies chronology and tamper evidence. It does not supply authorship, legal title or the truth of any claim — sources, definitions, dates and methodology do that work.
CLAIMS INVITE DEBATE. ARTIFACTS INVITE INSPECTION.
⛓ SOVEREIGN PROOF · ENTRY #172
THE SOVEREIGN LEDGER™ | ENTRY #172 | THE INSTANT SETTLEMENT ENGINE™ — FROM AGREEMENT TO VALUE™ | GEOFF DE WEAVER | LIMITLESS USA LLC | https://geoffdeweaver.com/instant-settlement-engine/ | 2026-09-25 ET | CORPUS: 172 ENTRIES
a201369e6a060877ff2568a00dacc45c298dd3bce1234df3d925ef37a2c720d4
This file’s SHA-256 is committed through OpenTimestamps. Once confirmed in a Bitcoin block, the proof shows that this exact document existed at or before that block time and has not been altered. The timestamp does not grant a license, transfer copyright, or replace registration.
SOURCES, CORRECTIONS & RIGHTS
Primary and institutional sources: ICE Mortgage Technology, Mortgage Monitor (May 2026) and MERS eRegistry announcement (March 11, 2026); American Land Title Association, 2026 Seller Impersonation Fraud study (September 14, 2026); U.S. District Court for the Eastern District of Texas, Flowers Title Companies, LLC v. Bessent (March 19, 2026); U.S. Department of the Treasury, GENIUS Act NPRM (August 18, 2026); Consumer Financial Protection Bureau, TILA-RESPA Integrated Disclosure rule; Fannie Mae eMortgage guidance; Property Records Industry Association; BIS Innovation Hub, Project Agorá (May and July 2026); The Clearing House RTP network; Federal Reserve FedNow Service; HSBC Tokenized Deposit Service (April 13 and June 22, 2026); J.P. Morgan Kinexys; McKinsey & Company tokenization outlook (June 2024); BCG and Ripple, Approaching the Tokenization Tipping Point (2025); Deloitte Center for Financial Services real estate tokenization prediction (2025); IDC Worldwide AI IT Spending Market Forecast (August 26, 2025); PwC 29th Global CEO Survey (January 2026); Bain & Company Technology Report 2025; Accenture payments research; Forrester 2026 Predictions and Consumer Pulse research; Starlink network update (July 2025); SpaceX and SoftBank Group 2026 materials; Statista Market Insights (Real Estate, Worldwide, 2026); Savills global real estate value (2025).
Reporting and data links:
NAR — ALTA 2026 Seller Impersonation Fraud Study
National Mortgage News — Seller Impersonation Tactics and Red Flags
Davis Wright Tremaine — FinCEN Residential Real Estate Rule on Hold
Jones Day — Treasury Proposes GENIUS Act Rules (August 2026)
ICE — MERS eRegistry Surpasses 3 Million eNotes
The Clearing House — RTP 2025 Volume
Mastercard / The Clearing House — RTP Q1 2026 Case Study
Digital Transactions — RTP Record Day and FedNow Limit Increases
Cointelegraph — BIS Project Agorá Real-Value Testing (July 2026)
HSBC — Tokenized Deposit Service Expands to the United States
HSBC — Tokenised Deposit Service Launches in the UAE
J.P. Morgan Kinexys — Volume and $10 Billion Daily Target
McKinsey — Tokenized Assets Toward $2 Trillion by 2030
BCG and Ripple — $18.9 Trillion by 2033
IDC — AI Spending to Reach $1.3 Trillion in 2029
PwC — 29th Global CEO Survey
Bain & Company — Technology Report 2025
Accenture Banking Blog — Payments Foundations Research
Infosecurity Magazine — Forrester Agentic AI Breach Prediction
The Register — Starlink Network Update (July 2025)
The Sovereign Ledger™ #171 — The Global Distribution Control Layer™
The Sovereign Ledger™ #170 — The Legal Control Layer™
The Sovereign Ledger™ #169 — The Authoritative Ownership Record™
The Sovereign Ledger™ #168 — The 7,000-Year War for the Ledger™
The Sovereign Ledger™ #167 — The Cost of Control™
The Sovereign Ledger™ #166 — The Sovereign Control Plane™
The Sovereign Ledger™ #161 — The Programmable Ownership Execution Standard™
The Sovereign Ledger™ #158 — The Model-Agnostic Sovereign Option™
The Sovereign Ledger™ — Complete Index
Fact and opinion: Figures, dates and quoted positions are attributed to their sources. Frameworks, forecasts of my own, interpretations and conclusions — including The Instant Settlement Engine™, the Verified Counterparty Rail™, the Conditions-to-Close Graph™, the Real Estate Friction Budget™, Settlement Efficiency™ and Atomic Real Estate Settlement™ — are my own analysis and opinion.
Corrections: If you believe any fact in this Entry is inaccurate, write to geoff@geoffdeweaver.com. Verified corrections are published as dated revisions; the original anchored version is preserved, never silently overwritten.
Not advice: Nothing in this Entry is legal, financial, tax or investment advice, or an offer or solicitation to buy or sell any security, token or property interest.
© 2026 Geoff De Weaver and Limitless USA LLC. All rights reserved. This Entry is a human-authored work. The Sovereign Ledger™, The Instant Settlement Engine™, From Agreement to Value™, The Sovereign Transaction Quad™, The Friction Paradox™, The Real Estate Friction Budget™, The Verified Counterparty Rail™, The Verified Counterparty Layer™, The Conditions-to-Close Graph™, T-0 Begins After T-Minus Everything™, Programmable Liquidity™, Atomic Real Estate Settlement™, The Settlement Flywheel™, From Closing to Compounding™, Settlement Efficiency™, The Settlement Control Plane™, The Brokerage Bridge™, The Ownership Value Chain™, Agent/Broker Operational Advantage™, The Global Distribution Control Layer™, The Legal Control Layer™, The Authoritative Ownership Record™, The Ownership Thesis™ and REALATAR™ are trademarks of Geoff De Weaver and Limitless USA LLC. No license is granted to copy, scrape, mine, republish, commercially reuse, or use this content to train, fine-tune or develop artificial-intelligence systems without written permission, except as permitted by applicable law. Text-and-data-mining and AI-training rights are expressly reserved, including under Article 4(3) of EU Directive 2019/790. Brief quotation with attribution and a link to the canonical URL is welcome.
ABOUT THE AUTHOR
Geoff De Weaver
Researcher · Architect · Limitless USA LLC
Architect of The Ownership Thesis™ & REALATAR™ | Building Horizontal Liquidity Rails for the $625T Global Real Estate Market | AI • Web3 • T-0 Atomic Settlement
I am Founder & CEO of Limitless USA LLC, architect of The Ownership Thesis™ and REALATAR™, and author of The Sovereign Ledger™ — a Bitcoin-anchored research corpus that, with publication of this Entry, comprises 172 entries and more than 2.62M verified words, alongside 800+ strategic blueprints on the future of ownership, capital markets, AI, blockchain and the approximately $625 trillion global real estate market. My work spans four decades across major U.S. and APAC financial and advertising centers, and it is published as a living, evolving primary-source record for institutional review.
Four decades. Four Big Four holding companies. One firm since 2010.
THE SOVEREIGN LEDGER™ #172
THE INSTANT SETTLEMENT ENGINE™
TRUTH → LAW → DEMAND → EXECUTION™
FROM AGREEMENT TO VALUE™ · OBSERVE · THINK · PROVE · BUILD